Blog Post
Data Drop: Not All Mezz Are Created Equal
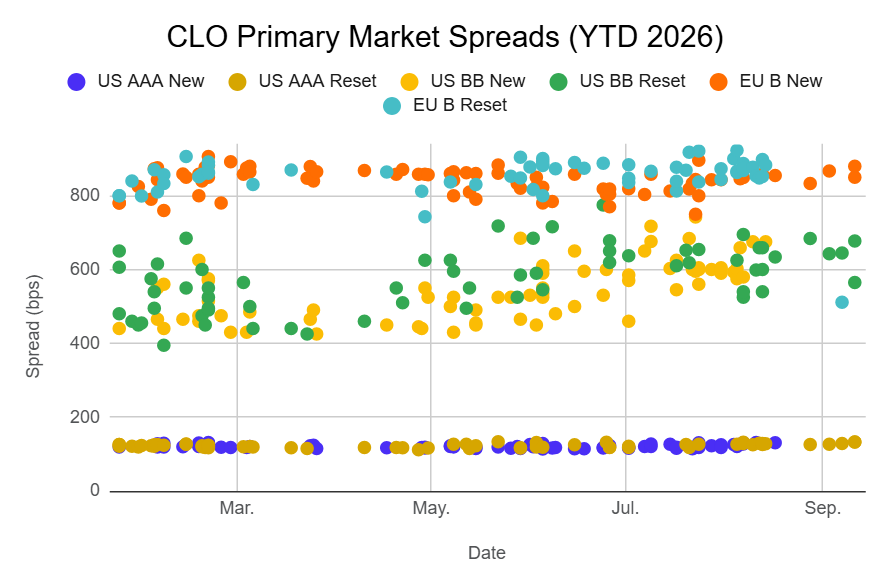
CLO spreads have proven remarkably resilient to broader market turmoil in recent years, with most shocks turning out to be short-lived. Today most parts of the capital structure are gradually tightening, trading at or near all-time tights, and with little tiering between managers.
At the very bottom of the rated capital structure – double-Bs in the U.S. and single-Bs in Europe – however, the picture is different, with spreads wider than at the start of 2026. These tranches have generally not recovered from their war-induced widening earlier in the year, and are showing much greater dispersion than their higher rated counterparts.
From a credit perspective, this is not too surprising. As the part of the capital structure most exposed to defaults other than the unrated equity, these tranches are subject to the idiosyncratic risks in a deal’s portfolio, and a small but meaningful proportion of them have market value overcollateralisation levels of less than 100$. Moreover, incoming regulatory changes are set to steepen the capital curve for U.S. insurers, historically major investors in mezzanine tranches, making double-B tranches much less attractive.
This publication has been prepared by Octus Intelligence, Inc. or one of its affiliates (collectively, "Octus") and is being provided to the recipient in connection with a subscription to one or more Octus products. Recipient’s use of the Octus platform is subject to Octus Terms of Use or the user agreement pursuant to which the recipient has access to the platform (the “Applicable Terms”). The recipient of this publication may not redistribute or republish any portion of the information contained herein other than with Octus express written consent or in accordance with the Applicable Terms. The information in this publication is for general informational purposes only and should not be construed as legal, investment, accounting or other professional advice on any subject matter or as a substitute for such advice. The recipient of this publication must comply with all applicable laws, including laws regarding the purchase and sale of securities. Octus obtains information from a wide variety of sources, which it believes to be reliable, but Octus does not make any representation, warranty, or certification as to the materiality or public availability of the information in this publication or that such information is accurate, complete, comprehensive or fit for a particular purpose. Recipients must make their own decisions about investment strategies or securities mentioned in this publication. Octus and its officers, directors, partners and employees expressly disclaim all liability relating to or arising from actions taken or not taken based on any or all of the information contained in this publication. © 2026 Octus. All rights reserved. Octus(TM) and the Octus logo are trademarks of Octus Intelligence, Inc.